The 38-month Extended Credit Facility (ECF) arrangement remains subject to approval by the IMF Executive Board, which is expected to consider the request in early December.
Niger also reached agreement on the 10th and final review of the current ECF programme.
Completing the review and approving the new arrangement would make about $36 million immediately available to meet external financing needs and support reform implementation.
Economic growth is projected at 7% in 2026 and 6.7% in 2027, driven mainly by agriculture and extractive industries.
Average growth is expected to reach approximately 6.1% over the medium term, supported by public investment and continued expansion in agriculture and mining.
Inflation is projected at -2.5% in 2026 before rising to 2.2% in 2027.
Higher oil prices linked to the Middle East conflict have strengthened Niger’s public finances and external position. However, increased transport costs are placing pressure on households, particularly vulnerable communities.
The fiscal deficit is projected at 3.4% of gross domestic product in 2026.
The deficit accommodates reconstruction following natural disasters in 2025 and assistance for households affected by high food and fuel prices.
The government is using part of the additional oil revenue to rebuild fiscal buffers while prioritising concessional financing and grants.
The IMF said Niger had performed strongly against programme targets for the end of June and continued clearing domestic and external arrears.
The proposed ECF programme will support Niger’s 2025-2029 Programme for the Refoundation of the Republic.
Priorities include increasing government revenue, safeguarding debt sustainability, strengthening financial stability and supporting more inclusive private-sector-led growth.
The programme will also focus on public financial management, governance, accountability, transparency and social cohesion.
Reforms are expected to strengthen banks’ ability to finance private companies, including micro, small and medium-sized enterprises.
However, the IMF warned that security challenges and climate shocks remained significant risks to the economic outlook.
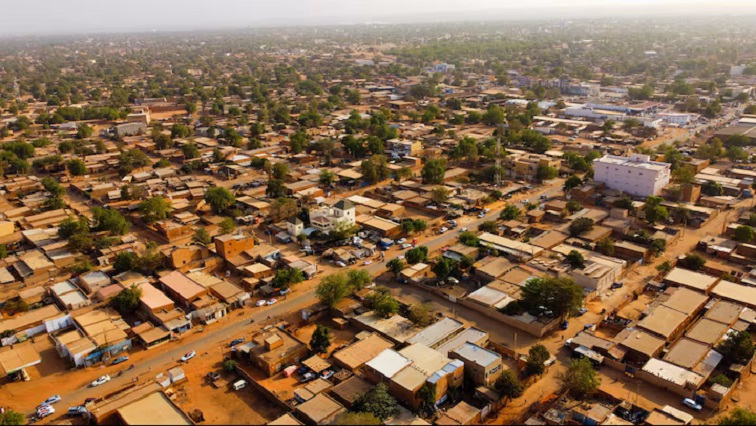
An IMF team led by Julia Bersch held discussions in Niamey from September 28 to October 8.
–IMF/ChannelAfrica–