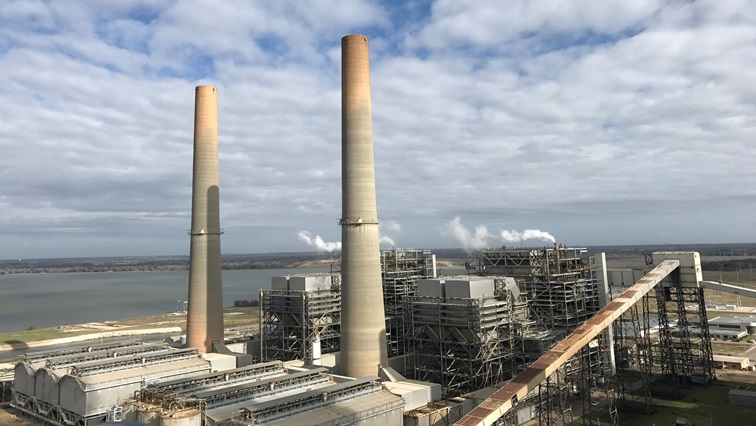
The IMF Working Paper distinguishes between actual energy shortages and geopolitical risk that creates expectations of future disruption.
Researchers developed a high-frequency model to separate changes driven by current demand, expected demand, physical supply disruption and geopolitical supply risk.
The analysis found that actual oil supply disruptions produced persistent increases in consumer prices and unemployment.
By contrast, oil-price increases driven by fears of future shortages had short-lived effects on consumer prices and no measurable effect on unemployment. Prices generally returned to pre-shock levels within six to 12 months.
A supply disruption that raised oil prices by 1% increased unemployment by about 0.03 percentage points after one year.
Natural-gas shocks had more persistent effects on European consumer prices, regardless of whether prices rose because of actual shortages or geopolitical fears. However, the effect on unemployment remained limited.
The researchers examined the Russia-Ukraine war, trade and production announcements in April 2025 and the 2026 Middle East war.
In March 2026, the Middle East conflict effectively closed the Strait of Hormuz, trapping about 20% of global oil and liquefied natural gas consumption in the Gulf.
Oil peaked at $126 a barrel before trading mainly between $90 and $110, while European liquefied natural gas prices reached almost three times the pre-war level by late September.
The study found that geopolitical fears drove energy prices higher before the conflict began. After physical disruption occurred, concern about additional shortages continued placing upward pressure on prices.
During the Russia-Ukraine war, geopolitical supply risk contributed more than twice as much as actual disruption to oil-price increases because physical oil losses were limited.
Gas markets experienced more significant physical disruption, producing a different price pattern.
The findings suggest central banks should avoid treating every energy-price increase as evidence of a physical shortage.
Tightening monetary policy aggressively in response to a temporary geopolitical risk premium could unnecessarily weaken economic activity.
Actual shortages may require a different response because the resulting inflation and employment effects are larger and more persistent.
–IMF/ChannelAfrica–